Solutions
Solutions for every insurance professional
The trusted technology partner to increase your insurance transactions. Eight audiences, one platform, and the parts of it that matter to each.
Solutions for MGUs and MGAs
Managing General Underwriters and Agents often manage complex insurance processes. Our cloud-based marketing, underwriting, binding and payment platform frees up your staff so they can advise customers instead of shuffling paperwork and forms.
Multi-channel
Run your insurance business across all sales channels, including web, tablet and mobile storefronts, and integrate with your social media presence.
Business growth
Leverage your customers' feedback to write more business, find the right markets and the right underwriters, quote, bind and accept payments.
Fast growing community
Source more relevant agent and broker partners from our proprietary database of close to one million professionals.
No tech team needed
Forms, payments and legal document generation are handled for you. Focus on your expertise.
Solutions for insurance agents & brokers
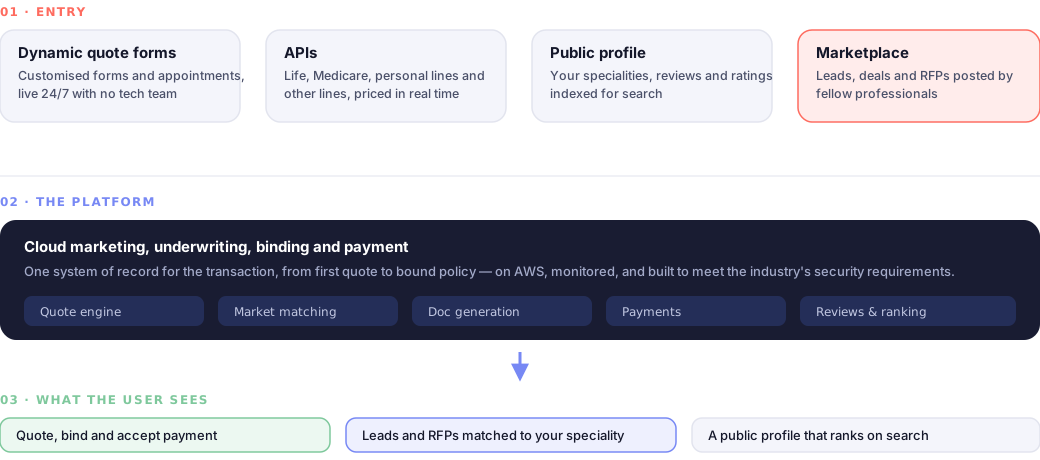
A global platform for insurance professionals. We operate a comprehensive cloud-based commerce platform designed for small and medium-sized insurance agents and brokers.
Leverage your customers' feedback to write more business, find the right underwriters, quote, bind and accept payments — and keep the customer afterwards through a public profile that ranks.
- A public profile with your specialities, address and opening times
- Reviews and ratings that raise your position in search results
- Source the right markets, or find professionals licensed in a state you are not
- Source leads, deals and RFPs posted by fellow professionals
Solutions for underwriters
The boost you need: stop competing on price alone.
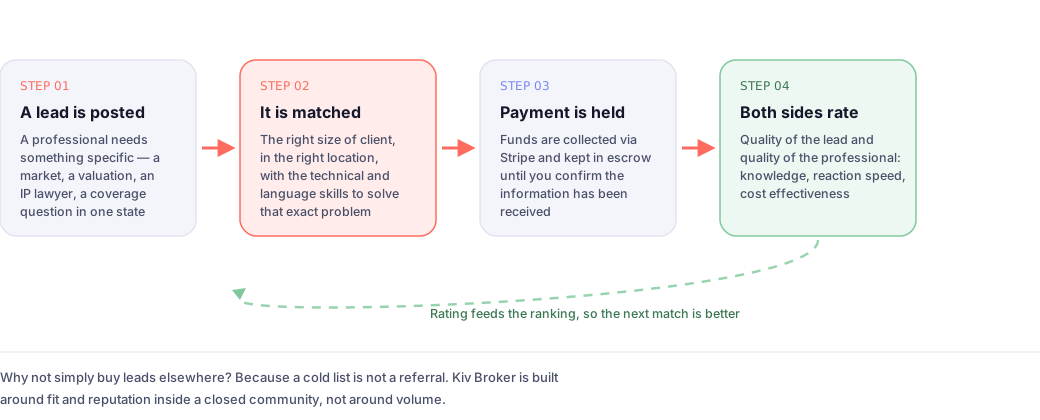
Network buildout. Showcase your recent wins, get feedback from brokers and expand your distribution network. Underwriters on Kiv Broker can present their capabilities to agents and brokers who are actively looking for a market — rather than waiting to be found in a rate table.
- Publish recent wins and appetite
- Collect structured feedback from the brokers who place business with you
- Expand distribution into states and specialities you do not cover today
What being on the platform changes
- DiscoveryYou are visible to the broker who needs you
- FeedbackStructured, not anecdotal
- ReachBeyond the states you know
Distribution is a two-way problem: brokers struggle to find the right market as much as underwriters struggle to be found.
04 · Partners
For partners, online retailers & tech platforms
Are you a tech company, a manufacturer, or a retailer interested in exploring, designing and offering custom insurance products for your customers?
We evaluate the options
Reach out and we will quickly work through the viable structures for your customer base and your product.
We navigate the regulation
Insurance is regulated by states, by the federal government, or by both depending on the line. We help you work out which applies to you.
We design the product
Custom insurance products for your customers, built with our network of MGAs and MGUs and embedded where your customers already are.
05 · Events & associations
For event organizers, clubs, associations & chambers of commerce
If you need an insurance solution to cover your events, Kiv Broker can help you.
We can build a product specifically tailored to your needs, at the best price, thanks to our network of MGAs and MGUs. That covers one-off events as well as the recurring cover an association or chamber needs for its members.
Tell us the event, the venue, the attendance and the exposure, and we will come back with the structures that fit rather than a single quote for a product that nearly fits.
06 · Financial institutions
For financial institutions
Are you a bank or a savings and loan association, a financial advisor, an asset manager or a lending platform? Do you need insurance solutions for your customers?
The same platform that carries a property and casualty quote can carry the cover that sits alongside a loan, a deposit relationship or a financial plan — with the compliance work handled on our side of the line.
Banks & thrifts
Cover distributed through a channel your customers already trust.
Advisors & asset managers
Protection adjacent to the advice you already give.
Lending platforms
Embedded cover at the point of approval.
Compliance
Designed around the rules that apply to your entity type.
07 · Manufacturers & dealers
Embed coverage in the product you sell
Do you manufacture a product? Do you want to embed insurance coverage as part of your product sales?
Embedded cover changes the economics of a sale: the customer gets protection at the moment they are most receptive, and the dealer gets a reason to keep the relationship after the warranty conversation. We handle the product design and the regulatory path.
Typical questions we work through
- Which line of coverage actually fits the product
- Who is the licensed party in each state you sell into
- How the cover is priced, disclosed and cancelled
- How the customer is served when something goes wrong
08 · RIAs & broker dealers
The Testimonial Rule is a product problem, not a legal one
Section 206(4) of the Advisers Act makes it unlawful for an RIA to engage in any act, practice or course of business which is fraudulent, deceptive or manipulative, and Rule 206(4)-1 identifies and effectively prohibits certain statements that, when published in an advertisement by an RIA, constitute a violation of the Act.
One of these prohibitions, the Testimonial Rule, prohibits the use of “any testimonial of any kind concerning the investment adviser or concerning any advice, analysis, report or other service rendered by such investment adviser.”
RIAs face certain challenges applying Rule 206(4)-1, which was originally adopted in 1961 and has not been substantially amended, to modern forms of communication. Kiv Broker is working on a solution to comply with Section 206(4) of the Advisers Act.
Explore solutions for RIAs and BDsWhy it is hard in practice
A rule written for printed circulars in 1961 now has to govern a review left on a public profile, a rating aggregated across a firm, and a recommendation exchanged between professionals.
The approach we are building treats the compliance constraint as part of the product design, so the firm does not have to police its own marketing channels after the fact.
Ready to get started?
Request a demo for free to see how we transform the insurance buying experience.